Calgary, Alberta
The mortgage fits. What about the rest?
A home has more than one monthly number. HomeCosts puts the less glamorous costs beside the mortgage, with room to compare two versions of life after move-in.
The mortgage number fits. You have checked it twice. It is tempting to close the calculator, go back to the photographs and decide where the sofa belongs. But the mortgage is not the only number moving in with you.
Utilities, insurance, property tax and any condominium or association fees have their own place in the household budget. So does the money you intend to set aside for maintenance. Two homes can look close in purchase price and leave you with different versions of an ordinary month.
HomeCosts.ca, part of our Real Estate Partners / PRPTY network, gives those other lines somewhere to sit. Its ownership-cost planner works from editable inputs and shows its calculations, with a separate comparison view for two scenarios. The purpose is a clearer conversation about costs, not a verdict on which home deserves an offer.
Start with your numbers, not the examples
The planner opens with illustrative figures already filled in. They are there to make the tool usable, not to tell you what a Calgary household typically pays. Replace them with the figures you can support and keep track of the ones you still need to confirm.
That distinction sounds small until a convenient example becomes a fact in your head. The last house you lived in may not be a useful stand-in for the next one. A condominium fee you remember seeing on another listing does not establish what is included here. Give each figure a reason to be in the budget.
The monthly total includes the maintenance reserve you enter. That reserve is money set aside, rather than a bill the planner has discovered. The annual figure multiplies the monthly total by twelve; adding the same reserve again would count it twice.
Change one thing and see what moves
The Compare tab carries your Plan inputs into Scenario A and puts a second set beside them. It separates upfront cash, monthly and annual carrying costs, and a five-year planning total. A smaller total is not automatically a better home for your household.
Try keeping the question modest. What happens if the utility figure changes? What does a different recurring fee do to the monthly picture? Changing one input at a time makes the comparison easier to understand than replacing everything and wondering which difference mattered.
You might finish with a clearer preference. You might instead finish with a short list of calls to make: one figure to confirm with the municipality, another with an insurer, another with the condominium documents. That is useful progress even when it does not produce an immediate decision.
A planning total is not money lost
The five-year view combines upfront cash with sixty months at unchanged assumptions. It is not a forecast of resale value or a calculation of profit and loss. Part of a mortgage payment repays principal, and future rates and expenses need not stay where the example leaves them.
The mortgage calculation is a planning approximation, not a lender quote. The tool's lending-rule assumptions also need confirmation with the appropriate professionals. Use it to organise questions and compare inputs; do not ask it to approve a loan, inspect a home or predict future bills.
Then go back to the photographs. You do not have to stop enjoying the home because you spent some time on the less exciting numbers. It is simply better to imagine the sofa with a little more of the household budget in view.
Continue reading
 Calgary market news
PRPTY resources · Sep 9, 2026
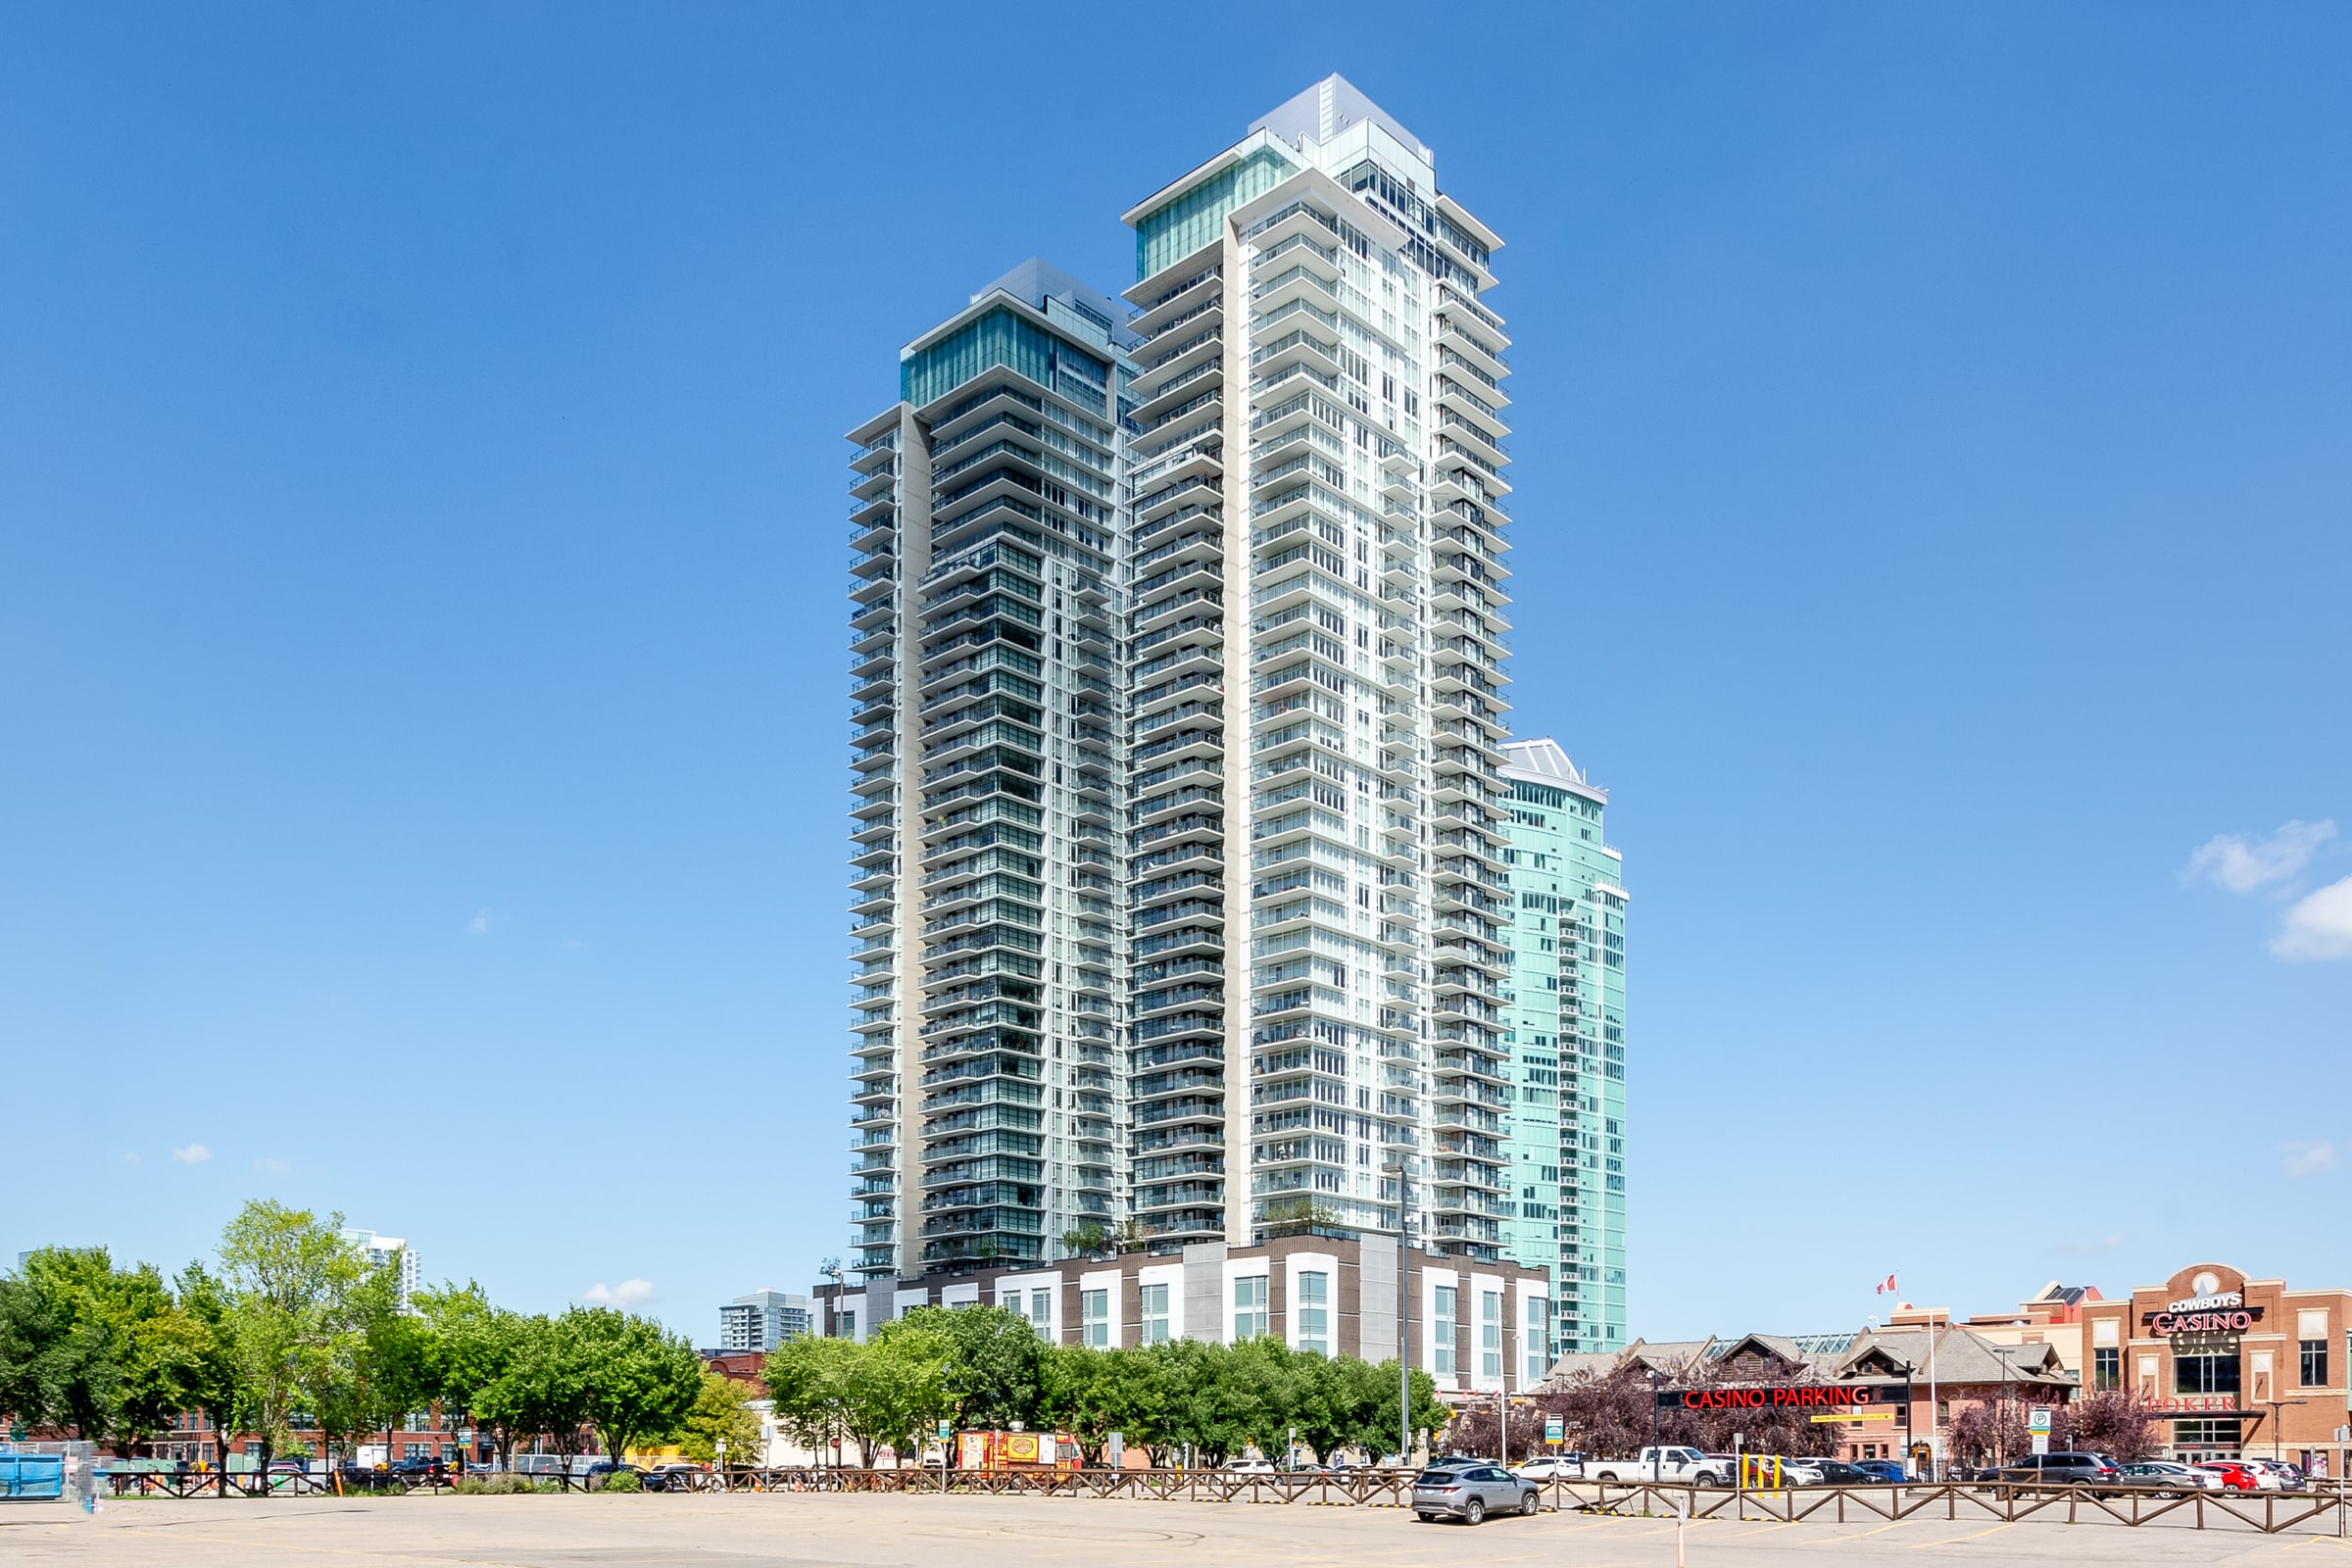
You fell for the kitchen. Now meet the building.
A good condo shortlist needs more than beautiful interiors. Our YYCCondos building guides help turn a few favourite photos into a more useful set of questions.
City and Policy · Looking back · Dec 3, 2025
The tax increase got smaller. The homeowner's budget still had more lines.
December's budget decision eased Calgary's proposed municipal tax increase. Reading it beside utility costs makes for a more useful household conversation.